Ave Maria New-Home Interest Rate Incentives: What Buyers Should Know in 2026
Last updated: September 2026
Interest rates can significantly affect the monthly cost of purchasing a home. That is one reason many buyers searching for new homes in Ave Maria, Florida, are paying close attention to builder financing incentives.
Builders may offer below-market mortgage rates, closing-cost assistance or other financial incentives on selected homes. These offers can sometimes make a new-construction home more affordable than a similarly priced resale property—but buyers must compare the complete financing package, not just the advertised interest rate.
Here is what buyers should know about Ave Maria new-home interest rate incentives in 2026.
Why Builder Mortgage Incentives Matter
The average interest rate for a conventional 30-year fixed mortgage was approximately 6.76% on September 10, 2026, according to Freddie Mac data published by the Federal Reserve Bank of St. Louis. Mortgage rates change regularly, and an individual buyer’s rate will depend on credit, down payment, loan type and other qualifications. View the latest Freddie Mac mortgage-rate data.
When market rates are elevated, a builder may help reduce the buyer’s borrowing cost by contributing money toward a mortgage-rate buydown through an affiliated or preferred lender.
Even a seemingly modest reduction in the interest rate can produce meaningful monthly savings. However, buyers should determine whether the advertised rate is permanent, temporary and available for the particular home they want to purchase.
What Is a Builder Interest Rate Incentive?
A builder interest rate incentive is generally a financing promotion offered on qualifying new homes when the buyer uses a participating lender and meets the program’s requirements.
Instead of reducing the home’s advertised price, the builder may contribute money that allows the lender to offer the buyer a lower mortgage rate.
Potential incentives may include:
- A permanently reduced fixed interest rate
- A temporary mortgage-rate buydown
- Assistance with allowable closing costs
- A credit that can be applied toward financing expenses
- A combination of financing and design incentives
- Special terms on selected quick move-in homes
The exact promotion may vary by builder, neighborhood, property, loan program and closing date.
Permanent Rate Buydowns Versus Temporary Buydowns
Not every advertised builder rate works the same way.
Permanent Mortgage-Rate Buydown
With a permanent buydown, the interest rate is reduced for the full term of the mortgage, assuming the buyer keeps the original loan.
This can provide predictable monthly principal-and-interest payments. Buyers should still review the loan estimate, annual percentage rate, lender fees and any points associated with obtaining the lower rate.
Temporary Mortgage-Rate Buydown
A temporary buydown reduces the effective interest rate during the first one, two or three years. The payment then increases according to the program’s schedule until it reaches the loan’s full note rate.
A common example is a 2-1 buydown:
- Year one: The payment is calculated at two percentage points below the note rate
- Year two: The payment is calculated at one percentage point below the note rate
- Year three and later: The buyer pays the full note-rate payment
A temporary buydown may help during the first years of homeownership, but the buyer must qualify for and be comfortable with the eventual full payment.
Which Ave Maria Builders May Offer Incentives?
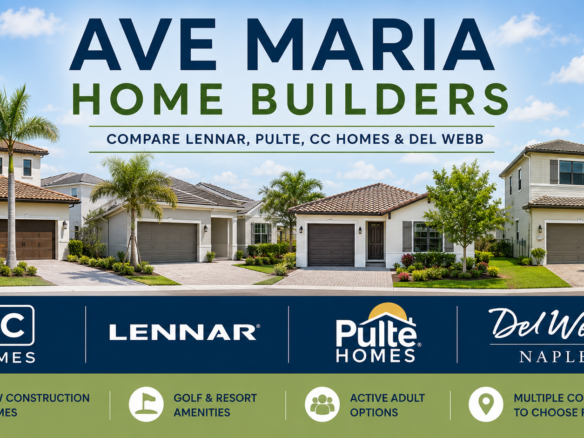
Ave Maria includes new homes from several builders and brands, including CC Homes, Lennar, Pulte Homes and Del Webb.
Financing promotions may be offered periodically in communities such as Maple Ridge, Silverwood, The National and Del Webb Naples. Availability can differ substantially among builders and may change without notice.
One builder might offer a reduced mortgage rate on a completed inventory home, while another may provide money toward closing costs or design selections. A promotion available on a quick move-in home may not be offered on a to-be-built floor plan.
This is why buyers should compare incentives at the property level rather than assume that every home from a particular builder qualifies.
Why Quick Move-In Homes Often Receive Stronger Incentives
Builders have already invested money in completed or nearly completed homes. If a quick move-in property remains available longer than expected, the builder may have a stronger reason to encourage a buyer to close by a particular date.
As a result, some of the most attractive Ave Maria builder incentives may be associated with:
- Completed inventory homes
- Homes approaching completion
- Properties with predetermined finishes
- Quarter-end or year-end closing goals
- Selected homes that must close by a stated deadline
The tradeoff is that buyers may have fewer opportunities to select flooring, cabinets, countertops and structural options. The potential financial incentive must therefore be weighed against the buyer’s preferred location, lot, floor plan and finishes.
Is the Lowest Interest Rate Always the Best Deal?
Not necessarily.
An advertised interest rate can attract attention, but it is only one component of the transaction. Buyers should compare the entire financial package, including:
- Purchase price
- Down payment
- Interest rate
- Annual percentage rate
- Mortgage points
- Origination and lender fees
- Closing costs
- Mortgage insurance
- Property taxes
- Homeowners insurance
- HOA and community fees
- Community Development District assessments, when applicable
- The cost of upgrades and options
For example, one builder might offer a lower rate but less flexibility on the purchase price. Another may offer a larger closing-cost contribution or a more attractively priced home without advertising the lowest rate.
The best option is the one that produces the strongest overall value for that particular buyer—not necessarily the offer with the most dramatic headline.
Does Every Buyer Qualify for the Advertised Rate?
No. Builder financing promotions usually contain eligibility requirements and restrictions.
The advertised rate may depend on:
- The buyer’s credit profile
- Loan type
- Down-payment amount
- Owner-occupancy requirements
- Maximum loan amount
- Use of the builder’s preferred lender
- Use of an affiliated title company
- A specific contract or closing deadline
- Selection of a qualifying home
- Available promotional funds
Some advertisements may also present a rate that requires payment of discount points. Buyers should ask whether the builder pays those points or whether any portion becomes the buyer’s responsibility.
A licensed mortgage professional should provide the buyer with the actual loan terms and qualification requirements.
Questions to Ask About an Ave Maria Builder Incentive
Before selecting a home based on an advertised financing promotion, ask the builder and lender:
- Is the rate permanent or temporary?
- What is the full note rate?
- What is the annual percentage rate?
- Does the offer require discount points?
- Who is paying those points?
- Which homes qualify?
- What credit score and down payment are required?
- Which loan programs qualify?
- Must the home close by a particular date?
- Is the incentive tied to the builder’s preferred lender or title company?
- Can the incentive be applied differently—for example, toward closing costs?
- Can the offer be combined with any other builder promotion?
- What will the complete monthly housing expense be, including taxes, insurance and community fees?
- What happens if construction or closing is delayed?
Ask for the answers and financing terms in writing whenever possible.
Should You Use the Builder’s Preferred Lender?
Using a preferred lender may be necessary to receive a particular builder incentive. That does not mean buyers should skip comparing alternatives.
Request a detailed loan estimate from the preferred lender and compare it with at least one outside lender. Look beyond the interest rate and compare:
- Cash required at closing
- Monthly principal and interest
- Annual percentage rate
- Lender charges
- Discount points
- Mortgage insurance
- Rate-lock terms
- Total projected borrowing costs
An outside lender may offer a more competitive standard loan, while the preferred lender may offer the stronger overall package after applying the builder’s contribution. Buyers will not know without comparing the numbers.
Why Bring Your Own Real Estate Agent?
The builder’s sales representative is there to sell the builder’s homes. Buyers can also work with their own licensed Florida real estate professional to help compare communities, properties and available incentives.
Your real estate agent can help you:
- Compare offers from different Ave Maria builders
- Identify qualifying quick move-in homes
- Evaluate the home price alongside the financing incentive
- Review HOA and community costs
- Compare lots, floor plans and finishes
- Ask questions about deadlines and restrictions
- Coordinate with your lender and other professionals
- Consider future resale value and marketability
Builder policies frequently require the buyer’s agent to accompany or register the buyer during the initial visit. Contact your agent before visiting a sales center, registering online or scheduling a builder appointment.
Your agent does not determine whether you qualify for financing and cannot provide mortgage approval. Loan qualifications and terms must come from the lender.
Are Ave Maria New-Home Incentives Worth Considering?
They absolutely can be—but every offer requires individual analysis.
A reduced rate may lower the monthly mortgage payment. Closing-cost assistance may reduce the amount of money needed at closing. A price reduction may provide more immediate equity and could affect future resale calculations differently.
The right choice depends on the buyer’s:
- Available cash
- Expected ownership period
- Loan qualifications
- Monthly-payment goals
- Preferred community
- Desired floor plan
- Plans to refinance if rates change
Rather than choosing a home based on a single advertised number, compare the complete cost of purchasing and owning each property.
Find Current Ave Maria Builder Incentives
Ave Maria builder incentives can change quickly, and the strongest offer may apply only to a limited number of homes.
Before visiting the builders, request the latest Ave Maria Builder Incentive Guide and a personalized comparison of qualifying new homes.
We are Florida-licensed real estate professionals who work independently from the builders. We can help you compare available homes and builder promotions across Ave Maria without being limited to one builder.
Call or text (239) 329-0918 to discuss current Ave Maria new-home opportunities or arrange a private builder tour.
Financing promotions, rates, prices and availability are subject to change without notice. This article is provided for general informational purposes and is not a commitment to lend or a substitute for advice from a licensed mortgage professional. Buyers must satisfy applicable lender and builder requirements.

Join The Discussion